



Florida Says Insurance Costs Are Falling. Are Residents Feeling It?

For Florida residents accustomed to opening insurance renewals with a sense of dread, an announcement of lower rates offers something unusual: the possibility of relief.
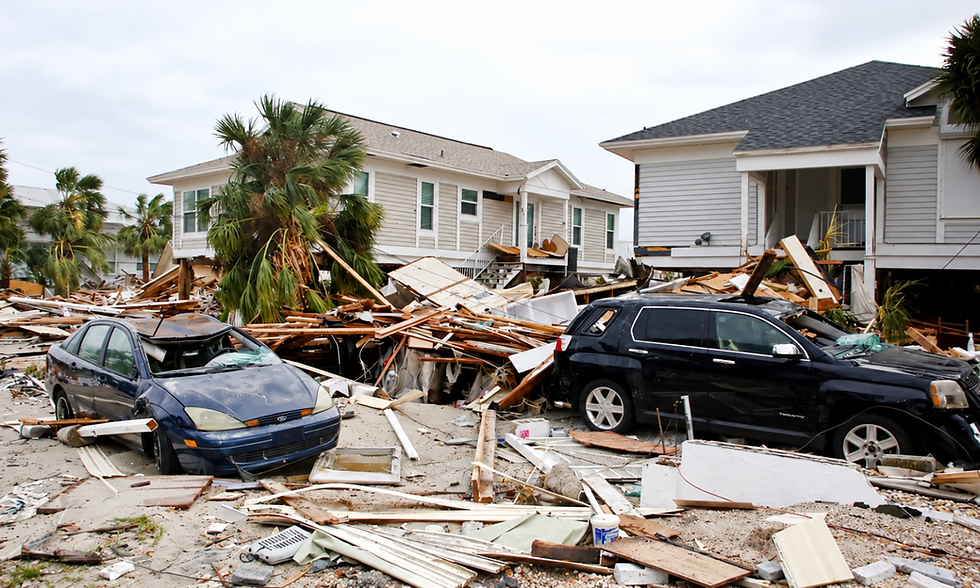
The Florida Office of Insurance Regulation announced October 2 that it had approved an average 12.8 percent rate reduction affecting more than 120,000 rental insurance policies, effective this month. The announcement followed a September 22 release describing significant homeowners insurance rate decreases. These are reductions for particular policies, rather than a statewide guarantee that every household’s premium will fall.
The question for Tampa Bay residents is straightforward: When will those announcements translate into a smaller bill?
An approved rate reduction and an individual customer’s renewal premium measure different things. A rate is part of the calculation used to price coverage. The final premium also reflects the property, coverage limits, deductibles and other policy characteristics. A household’s circumstances can change between renewals, complicating a simple comparison.
That distinction matters because residents experience insurance through dollars leaving their accounts. A percentage reduction sounds encouraging, but the practical benefit depends on the starting price and the coverage attached to it.
For a family balancing a mortgage, groceries and transportation, even modest savings could provide breathing room. For someone whose premium previously climbed sharply, a reduction may feel more like recovering lost ground than receiving a financial windfall.
The most useful test is a comparison of renewal documents. Does the new policy cover the same property for the same amount? Has the deductible changed? Are there exclusions that were not present before? A lower premium becomes less reassuring if it accompanies less protection.
Those questions also help separate meaningful improvement from marketing. The number at the bottom of the bill deserves attention, but so do the conditions under which the insurer would pay a claim.
Renters and homeowners face different insurance needs, making it especially important not to treat announcements about one category as evidence of relief across the entire market. The October announcement’s rental-policy reduction should not be read as a matching decrease for every homeowners policy.
There is also a broader affordability question. Insurance is one expense within a housing budget. Even when that expense declines, other costs can keep total household spending elevated. Residents may welcome a better renewal while still feeling financially stretched.
For Tampa Bay, the human story lies in that gap between an improving headline and an individual budget. A household receiving a substantial reduction, another receiving little change and a third facing an increase could all have different experiences during the same period.
The state’s announcements provide a reason to examine the market more closely. They do not, by themselves, establish how widely residents are benefiting.
A convincing measure of recovery would be sustained, comparable savings across renewal cycles, accompanied by coverage residents understand and can afford to maintain.
Until then, Florida’s insurance relief will be judged where it matters most: at kitchen tables, where families open their bills and decide what they can pay.


Comments